Quick Answer
A FAIR Plan is a state-authorized insurance pool that sells stripped-down property coverage to homeowners that private insurers have refused to write, usually because of wildfire, hurricane, or hail exposure. Every licensed insurer doing business in the state has to belong to it, and every FAIR Plan can bill its own member insurers, and often ordinary policyholders statewide, when claims outrun premiums. As of 2026, roughly three dozen states run some version of this backstop, and the two largest pools — California’s FAIR Plan and Florida’s Citizens Property Insurance Corporation — together cover more than a million homes that the voluntary market wouldn’t touch.
Why State Insurers of Last Resort Are Suddenly Everyone’s Problem
For most of their history, FAIR Plans were a quiet corner of the insurance world, a niche backstop for a small number of homes in flood-prone city blocks or coastal strips that no ordinary carrier wanted on its books. That changed over the past six or seven years. Wildfire losses in the western United States, repeated hurricane landfalls along the Gulf Coast, and a jump in reinsurance costs pushed private insurers to pull back from entire zip codes rather than reprice their way through the risk. When a carrier declines to renew a policy or refuses new business in a county, the homeowner doesn’t simply go without insurance — most mortgage lenders require it, so the homeowner lands in the state’s residual market, which in most cases means a FAIR Plan.
The scale of that shift is no longer a rounding error. California’s FAIR Plan held around 140,000 policies in 2018. By the end of 2024 it had grown past 550,000, and its total exposure — the dollar value of everything it insures — had climbed past $600 billion, a level that would have been unthinkable a decade earlier for what was designed as a niche backstop. Florida’s Citizens Property Insurance Corporation swelled even faster in relative terms, ballooning from roughly 420,000 policies in 2019 to a peak above 1.3 million in late 2023, before a state-run depopulation effort pushed private insurers to take some of those policyholders back. Louisiana’s residual market grew after a wave of small regional insurers went insolvent following Hurricanes Laura, Delta, and Ida. None of this happened because homeowners suddenly became worse risks overnight. It happened because the private market’s appetite for catastrophe exposure shrank faster than the exposure itself did.
That matters well beyond the households actually enrolled in a FAIR Plan. Because these pools are funded through assessments on member insurers, and because insurers in most states are allowed to pass some or all of an assessment on to their own policyholders, a bad wildfire season in one part of a state can quietly raise premiums for people who live nowhere near the fire and have never filed a claim. Understanding how the mechanism works — who pays, who is covered, and what gets left out — has become basic financial literacy for anyone who owns property in a state with meaningful catastrophe risk, which today includes far more of the country than it used to.
What a FAIR Plan Actually Is, and How It Got Here
The FAIR Plan concept dates to 1968, when Congress passed the Urban Property Protection and Reinsurance Act after a wave of civil unrest left insurers unwilling to write policies in many American inner cities. The federal law encouraged states to set up “Fair Access to Insurance Requirements” plans, giving residents of high-risk urban areas a path to basic fire insurance even when no private carrier wanted the business. States adopted the model at different paces, and today roughly 32 states plus the District of Columbia run some version of a FAIR Plan, though a handful of others use differently named residual-market mechanisms — Florida’s Citizens, Texas’s Windstorm Insurance Association, and North Carolina’s Joint Underwriting Association all perform a similar function under different names and different rules.
The basic structure is consistent across states even where the branding differs. A FAIR Plan is not a government agency and it does not spend taxpayer dollars to operate. It is a private, nonprofit pool that every insurer licensed to sell property coverage in the state must join by law, and every member insurer contributes to the pool’s losses in proportion to its share of the state’s overall property insurance market. In practice this means a large national insurer with fifteen percent of a state’s homeowners market absorbs roughly fifteen percent of that state’s FAIR Plan deficit in a bad year, regardless of whether that insurer ever wrote a single FAIR Plan policy itself.
California FAIR Plan: Policies in Force, 2018–2025
Approximate year-end counts, in thousands of policies
~140k
~200k
~345k
~555k
~ 700k
Figures are rounded approximations drawn from published FAIR Plan policy-in-force disclosures and industry reporting; exact quarterly totals fluctuate.
That funding model is the single most important thing to understand about a FAIR Plan, because it flips the usual logic of insurance on its head. In the voluntary market, an insurer prices a policy to cover the risk it is taking on that specific property. In a FAIR Plan, the premium a policyholder pays rarely covers the full cost of the risk in a bad catastrophe year, and the shortfall gets pushed backward onto every other insurer in the state, most of whom then push at least part of it forward onto their own customers. Nobody in this chain is losing money out of charity. They are absorbing a mandatory cross-subsidy that state law requires as the price of being allowed to sell insurance there at all.
What a FAIR Plan Covers, and the Gap You Inherit
The coverage sold through a FAIR Plan is deliberately narrower than a standard homeowners policy, and this is the detail that catches the most people off guard. A typical private-market HO-3 policy bundles together fire, wind, hail, theft, liability, water damage from plumbing failures, and additional living expenses if the home becomes uninhabitable. A basic FAIR Plan policy historically covered only fire, lightning, and internal explosion — nothing else. Most states have since expanded the standard FAIR Plan form to add wind and smoke damage, and California added a broader “Comprehensive” option in 2023 that layers on theft, water damage, and liability for an additional premium. But in most states, the base policy still leaves out at least one major peril, and the policyholder has to shop separately for what is called a Difference in Conditions policy, or DIC, to fill the gap.
A DIC policy is sold by a private surplus-lines carrier and wraps around the FAIR Plan’s fire-only coverage to add the perils the FAIR Plan doesn’t cover: theft, liability, water damage, and loss of use. Buying a DIC policy is not optional in any meaningful sense for a homeowner with a mortgage, because most lenders require liability coverage and comprehensive protection as a condition of the loan, and a bare FAIR Plan fire policy does not satisfy that requirement on its own. The result is that a homeowner pushed into the residual market usually ends up managing two separate policies, from two separate carriers, with two separate renewal dates and two separate claims processes, for coverage that a standard policy used to bundle into one.
Dwelling coverage limits have been rising, but they still lag replacement cost in expensive markets
California’s FAIR Plan raised its maximum per-dwelling limit to $3 million in 2023, up from $1.5 million, specifically because so many homes in high-value wildfire-adjacent markets like Malibu, the Oakland hills, and parts of the Sierra foothills exceeded the old cap. Even at $3 million, a homeowner with a custom-built house that would cost more than that to rebuild has to either accept a coverage gap or, more commonly, layer a separate excess policy on top of the FAIR Plan limit. Most states’ plans cap dwelling coverage well below California’s ceiling — commonly in the $500,000 to $1 million range — which can leave higher-value homes underinsured relative to actual rebuilding costs, especially after a wave of regional construction-cost inflation following a major disaster.
Commercial and multi-family exposure has grown just as fast as residential
Less discussed than the homeowner side is how much commercial exposure has piled into these pools. Small apartment buildings, strip malls, and mixed-use properties in wildfire and hurricane zones have been non-renewed by private commercial carriers at rates similar to, and in some California counties higher than, single-family homes. FAIR Plans generally do write commercial policies, but at lower per-location limits than large landlords need, which pushes multi-property owners into buying several overlapping FAIR Plan policies or seeking specialty coverage in the excess and surplus lines market at substantially higher rates.
How the Assessment Mechanism Spreads the Bill to Everyone
The part of this system that surprises people who have never filed a FAIR Plan claim is that they can still end up paying for someone else’s. When a FAIR Plan’s losses in a given year exceed its premium income, its reserves, and whatever reinsurance it purchased, state law allows it to levy an assessment against its member insurers. Because membership is mandatory for every company selling property insurance in the state, that assessment lands on every insurer regardless of size, and most state insurance codes then allow the insurer to recoup some or all of that assessment from its own policyholders through a surcharge, sometimes labeled separately on the bill and sometimes folded into the base premium at renewal.
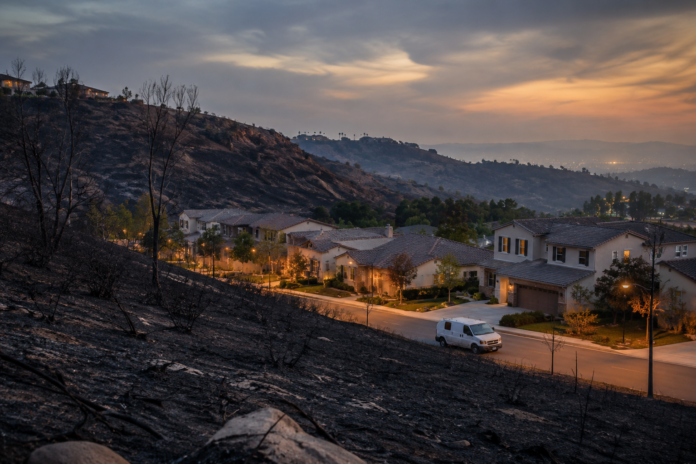
The clearest recent example came out of the January 2025 Los Angeles-area wildfires. The Palisades and Eaton fires generated FAIR Plan claims that state regulators estimated at roughly $4 billion, a sum that exceeded the plan’s available reserves and reinsurance layer combined. California’s insurance commissioner approved a $1 billion assessment against FAIR Plan member insurers in February 2025 under a regulatory mechanism known as an Emergency Assessment, and under existing California rules, insurers were permitted to recover up to half of that amount from policyholders statewide — not just policyholders in the burned areas, and not just FAIR Plan policyholders, but essentially anyone holding a residential or commercial property policy anywhere in the state. A homeowner in San Diego with no wildfire exposure whatsoever and a spotless claims history could see a line-item surcharge on a renewal notice traceable directly to fires that happened four hundred miles away.
Florida’s version of this mechanism is, if anything, more aggressive in its reach. Citizens Property Insurance Corporation can levy a “regular assessment” on its own policyholders first, then a “market equity surcharge” on the broader property insurance market, and finally an “emergency assessment” that can apply to nearly every kind of property and casualty policy sold in the state — auto insurance included — for up to ten years following a severe deficit year, capped at 10 percent of premium per assessment layer per year, up to a combined statutory ceiling. Every driver and homeowner in Florida effectively co-signs a very long-dated, adjustable-rate loan to a state insurance pool they may never interact with directly.
Eligibility Rules: Who Actually Ends Up in the Residual Market
FAIR Plans are explicitly a market of last resort, and most state statutes require an applicant to show they were declined, non-renewed, or offered coverage on materially worse terms by a set number of private insurers — commonly two or three — within a recent window, often the preceding sixty to ninety days. Applicants do not need to prove financial hardship or meet an income test; eligibility is about insurability in the private market, not about the applicant’s finances. In wildfire-designated high-severity zones, and along much of the hurricane-exposed Gulf and Atlantic coastline, entire ZIP codes can effectively qualify as a class, because private carriers have stopped writing new business there altogether rather than evaluate applications case by case.
Premiums on a FAIR Plan policy are regulated by the same state insurance department that oversees the voluntary market, but they are set to reflect the pool’s actual loss experience in that risk category, which in wildfire and coastal wind zones runs well above what a similar policy would have cost from a private carrier five years earlier. It is common for a FAIR Plan premium in a high-severity fire zone to run 1.5 to 3 times what the same dwelling would have cost to insure through the voluntary market before non-renewals became widespread, and that gap tends to widen each time the plan itself gets hit with a large loss year and has to file for a rate increase to rebuild reserves.
The Depopulation Problem
Every FAIR Plan’s stated long-term goal is to shrink itself, not grow. States run “depopulation” or “take-out” programs that pay private insurers a bounty, sometimes funded partly by the FAIR Plan itself, to review the pool’s existing policyholders and offer to write them back into the voluntary market. Florida’s depopulation program pulled roughly 400,000 policies out of Citizens between 2023 and the end of 2025 as several new and re-entering carriers absorbed blocks of policies. California has struggled to run an equivalent program at meaningful scale, in part because the underlying wildfire risk that pushed homeowners into the FAIR Plan in the first place hasn’t gone away, and private insurers remain reluctant to take back exactly the properties the FAIR Plan was built to hold. A plan that cannot depopulate tends to keep growing, which is exactly what has happened in California over the past several years.
Worked Example: Insuring a $600,000 Home in a High-Severity Wildfire Zone
Numbers make the mechanics concrete. Consider a homeowner in a hillside California community with a home valued at $600,000 for insurance purposes, previously insured through a standard voluntary-market HO-3 policy at $2,200 a year. In late 2024 the insurer sent a non-renewal notice, citing the county’s high-severity fire hazard designation. The homeowner shopped four other carriers, was declined by all four, and applied to the California FAIR Plan, which is the standard path once an applicant can document at least two declinations.
Cost Comparison: Standard Market vs. FAIR Plan + DIC Wrap
| Prior standard HO-3 policy (annual) | $2,200 |
| FAIR Plan basic fire policy, $600,000 dwelling | $3,850 |
| DIC wrap policy (liability, theft, water, loss of use) | $1,650 |
| New combined annual cost | $5,500 |
| Net effect: coverage cost rose roughly 150%, and the homeowner now manages two policies with two renewal dates instead of one. | |
The math gets more uncomfortable once the deductible structure is factored in. The prior HO-3 policy carried a flat $2,500 deductible for any covered loss. The FAIR Plan policy, like most in wildfire zones, carries a percentage-based wildfire deductible of 5 percent of the dwelling limit, which on a $600,000 structure works out to $30,000 the homeowner must cover before any FAIR Plan payout begins. Buying that deductible down to a flat $5,000 through an available buy-back endorsement added roughly $900 to the annual premium, bringing the realistic all-in cost, including the deductible buy-back, to about $6,400 a year — nearly triple the original policy, for coverage that most homeowners would consider a downgrade in claims-handling reputation and breadth of protection.
Run the same math across a neighborhood of two hundred similar homes and the aggregate cost increase for that one block alone exceeds $850,000 a year, money that used to flow to a single national insurer and now splits across a state-mandated pool, a surplus-lines DIC carrier, and, indirectly through assessments, every other property insurance customer in the state.
State-by-State Comparison of Major Residual Market Plans
| Plan / State | Perils Covered | Max Dwelling Limit | Approx. Policies (2025) | Funding / Assessment Reach |
|---|---|---|---|---|
| California FAIR Plan | Fire, smoke; comprehensive add-on since 2023 | $3,000,000 | ~700,000 | Insurer assessment; up to 50% recoupable from statewide policyholders |
| Florida Citizens | Multi-peril, near-standard HO form | No hard statutory cap; underwriting-based | ~900,000 | Regular + emergency assessments on nearly all P&C lines, up to 10 years |
| Texas Windstorm Insurance Assoc. | Wind and hail only, 14 coastal counties | $1,970,000 (indexed) | ~290,000 | Catastrophe reserve fund, reinsurance, capped member assessments, public bonds |
| Louisiana Citizens | Wind, hurricane, fire | $1,000,000 | ~100,000 | Regular assessment on member insurers, emergency assessment on policyholders statewide |
| NC Joint Underwriting Assoc. / Beach Plan | Fire (JUA); wind/hail coastal (Beach Plan) | $750,000 | ~200,000 combined | Member insurer assessment proportional to market share |
Two patterns stand out across every row of that table. First, the plans covering the broadest perils — Florida’s Citizens most of all — carry the broadest assessment reach, because a pool that behaves like a full-service insurer needs a correspondingly large backstop when its losses run high. Second, every plan without exception relies on the same core idea: risk that the private market has priced out is not eliminated, it is redistributed across a wider group of people who did not choose to take it on.
Common Mistakes Homeowners Make With Last-Resort Coverage
Homeowners pushed into a FAIR Plan for the first time tend to make the same handful of errors, usually because they assume the new policy behaves like the old one.
- Skipping the DIC wrap policy. Some homeowners see the FAIR Plan premium, decide it is expensive enough already, and skip the liability and theft wrap coverage entirely. This leaves them without liability protection if a visitor is injured on the property, and without theft coverage, which a standard policy would have included by default.
- Assuming the percentage deductible works like a flat one. A 5 or 10 percent wildfire or hurricane deductible on a $700,000 home means $35,000 to $70,000 out of pocket before the policy pays a dollar. Homeowners who don’t run that calculation in advance are frequently blindsided at claim time.
- Not shopping the voluntary market every renewal. Eligibility for a FAIR Plan doesn’t have to be permanent. Insurers periodically re-enter zip codes, especially after wildfire mitigation work like defensible-space clearing or a Class A roof replacement, and a homeowner who never checks again can overpay for years after cheaper private coverage became available.
- Underestimating replacement cost and hitting the coverage cap. Construction costs after a regional disaster can jump 20 to 40 percent within eighteen months due to labor and material shortages, which means a FAIR Plan limit that looked adequate at binding can fall well short of actual rebuild cost by the time a claim is filed.
- Ignoring mitigation credits. Many FAIR Plans now offer premium discounts of 5 to 20 percent for documented wildfire hardening measures — ember-resistant vents, non-combustible roofing, defensible space certification — and a large share of eligible policyholders never apply for them.
Practical Checklist Before You Accept a FAIR Plan Policy
- Confirm you have documented declinations from at least the number of voluntary-market carriers your state requires, and keep the denial letters on file.
- Get a DIC quote from at least two surplus-lines brokers before binding the FAIR Plan policy, so the combined cost is clear up front rather than discovered after the fact.
- Ask specifically whether your policy carries a percentage deductible for wildfire, hurricane, or named-storm events, and calculate the dollar amount in your own numbers rather than trusting the percentage alone.
- Verify the dwelling limit against a current, local replacement-cost estimate, not the home’s market value or purchase price, which usually understate rebuild cost in high-cost regions.
- Ask your agent about mitigation credits available in your state and gather the documentation — inspection reports, receipts, photos — needed to claim them at the next renewal.
- Set a calendar reminder to re-shop the voluntary market at every renewal, since insurer appetite in a given zip code can change year to year.
- Check whether your state’s plan publishes a depopulation or take-out list, and ask your agent whether your policy is a candidate to move back to a private carrier.
- Review your annual renewal notice for a line-item assessment surcharge, even if you were never a FAIR Plan policyholder yourself, since standard-market policies can carry pass-through charges too.
Key Takeaways
- A FAIR Plan is a mandatory, insurer-funded pool of last resort, not a government insurance program, and it exists in some form in roughly 32 states plus the District of Columbia.
- Coverage is narrower than a standard policy in most states, commonly excluding liability, theft, and water damage, which forces homeowners to buy a separate Difference in Conditions wrap policy.
- When a FAIR Plan’s losses exceed its reserves, it assesses member insurers, who are typically allowed to pass some or all of that cost on to their own policyholders statewide, spreading the bill far beyond the affected disaster area.
- California’s FAIR Plan grew from about 140,000 policies in 2018 to roughly 700,000 by 2025, driven almost entirely by wildfire-related non-renewals in the voluntary market.
- Percentage-based catastrophe deductibles, often 5 to 10 percent of the dwelling limit, can mean tens of thousands of dollars in out-of-pocket cost before a FAIR Plan policy pays anything.
- Depopulation programs exist to shrink these pools by moving policyholders back to private insurers, but they only work in states where the underlying catastrophe risk is being actively mitigated.
Frequently Asked Questions
What is a FAIR Plan in insurance terms?
A FAIR Plan is a state-mandated insurance pool that provides basic property coverage to homeowners and businesses that private insurers have declined to cover, typically because of wildfire, hurricane, or other catastrophe risk. Every insurer licensed to sell property coverage in that state is required to participate in and help fund the plan.
Is a FAIR Plan the same as government insurance?
No. A FAIR Plan is not funded by tax dollars and is not run as a government agency, even though it operates under state law and regulatory oversight. It is a nonprofit pool capitalized by mandatory contributions from private insurance companies doing business in the state.
Why is FAIR Plan insurance more expensive than a regular policy?
FAIR Plan premiums are priced to reflect the actual loss experience of the riskiest properties in a state’s insurance market, which is why they often run 1.5 to 3 times higher than a comparable voluntary-market policy. Separate wrap coverage for perils the FAIR Plan doesn’t include adds further cost on top of that base premium.
Do I need additional insurance on top of a FAIR Plan policy?
In most states, yes. A basic FAIR Plan policy typically covers only fire, smoke, and a limited set of perils, so homeowners usually need a separate Difference in Conditions policy to add liability, theft, water damage, and loss-of-use coverage that a standard homeowners policy would normally include.
Can I get out of a FAIR Plan once I’m in it?
Yes, if a private insurer becomes willing to write your property again, often after wildfire mitigation work or through a state-run depopulation program that transfers policies from the FAIR Plan back to voluntary-market carriers. It’s worth re-shopping coverage every renewal period rather than assuming FAIR Plan enrollment is permanent.
Will I pay for FAIR Plan losses even if I’m not enrolled in it?
Possibly. When a FAIR Plan’s losses exceed its reserves, it can assess its member insurers, and many states allow those insurers to recover part of that assessment through surcharges on their own policyholders, including people who have never been FAIR Plan customers and live far from the disaster that triggered the shortfall.
References
- California Department of Insurance, FAIR Plan oversight and rate filings, insurance.ca.gov.
- California FAIR Plan Association, policy-in-force and exposure disclosures.
- Florida Office of Insurance Regulation, Citizens Property Insurance Corporation depopulation and assessment reporting, floir.com.
- Texas Department of Insurance, Texas Windstorm Insurance Association statutory framework, tdi.texas.gov.
- Louisiana Department of Insurance, Louisiana Citizens Property Insurance Corporation plan of operation.
- National Association of Insurance Commissioners, residual market and FAIR Plan mechanics overview, naic.org.
- Insurance Information Institute, trends in homeowners insurance availability and residual markets, iii.org.
Homeowners navigating a FAIR Plan transition often need to rebuild their broader disaster budget at the same time, since a higher premium and a percentage deductible both change how much cash reserve a household needs on hand before the next wildfire or storm season.