Quick Answer
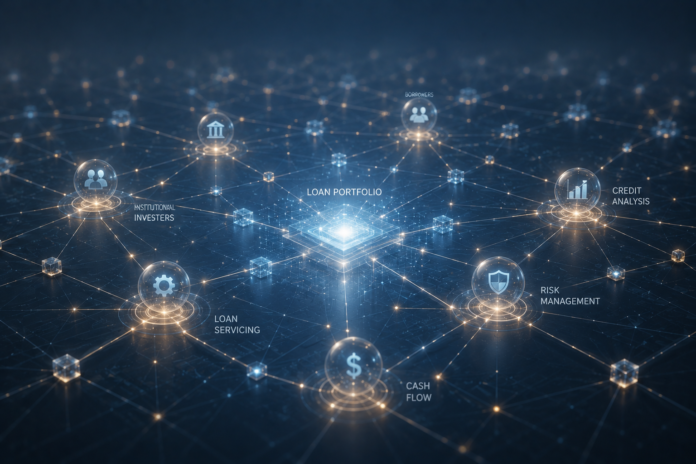
A tokenized private credit fund takes an ordinary direct-lending or asset-backed loan portfolio and represents each investor’s stake as a blockchain-recorded token instead of a paper limited partnership interest. The loans themselves, the fees, the accreditation rules, and the multi-year lockups are essentially unchanged — what moves on-chain is the ownership ledger, the subscription and transfer workflow, and, in a handful of programs, a thin secondary market. As of mid-2026, funds from sponsors including Apollo, KKR, Hamilton Lane, and Figure Technologies have tokenized a combined multi-billion-dollar slice of private credit, mostly still restricted to accredited or qualified purchasers, with target net yields commonly in the 9% to 13% range after fees.
Why Private Credit Is Migrating Onto Blockchains Right Now
Private credit grew from a niche corner of alternative investing into a roughly $1.7 trillion global asset class over the past decade, filling the gap left by banks that pulled back from leveraged lending after the 2008 crisis and again after the regional-bank stress of 2023. Direct lenders such as Ares, Blue Owl, and Blackstone Credit now originate loans that once sat exclusively on bank balance sheets, and they have raised enormous closed-end vehicles to do it. The problem sponsors ran into was distribution: these funds are sold almost entirely through institutional channels and private banks, with subscription documents, wire transfers, and capital-call notices that still resemble a 1995 workflow.
Tokenization entered the conversation as a fix for that back-office friction rather than as a way to reinvent credit underwriting. When Apollo and Securitize launched the tokenized share class of the Apollo Diversified Credit Fund on the Provenance blockchain in January 2025, the pitch was not a new asset class — it was the same diversified credit portfolio, but with subscriptions, capital account statements, and transfer-agent recordkeeping running through smart contracts instead of a transfer agent’s spreadsheet. KKR followed with a tokenized feeder into its Health Care Strategic Growth Fund II, and Hamilton Lane tokenized access to several of its flagship private markets funds, in each case lowering the practical investment minimum from the traditional $5 million-plus institutional check to figures closer to $20,000 to $100,000 depending on the platform and jurisdiction.
At the same time, a separate lineage of tokenized private credit grew up natively in crypto markets. Figure Technologies, which has originated more than $12 billion in home equity lines of credit, moved loan-level recordkeeping onto its own Provenance chain years before Wall Street asset managers took notice, and it later issued YLDS, a yield-bearing token registered with the SEC as a security whose return is linked to a portfolio of short-duration credit assets. Maple Finance and Centrifuge built lending pools where crypto-native lenders fund real-world borrowers or securitized pools directly, without a traditional fund wrapper sitting in between. Both lineages now describe themselves with the same phrase — tokenized private credit — even though the legal plumbing underneath differs substantially, which is exactly the kind of detail that trips up investors comparing products at a glance.
What Actually Gets Tokenized: The SPV, the Feeder, and the Whitelist
Nothing about securities law changes because a fund uses a blockchain. A tokenized private credit fund is still, in nearly every case, a private placement under Regulation D or a registered fund structure, and the loans inside it are still originated, underwritten, and serviced by conventional credit teams. What tokenization changes is the record of who owns what, and how that record moves.
The Wrapper: SPV or Feeder Fund
Most tokenized institutional credit products use a two-layer structure. A master fund holds the actual loan portfolio and is managed exactly as a traditional private credit fund would be, with an investment committee, a credit facility, and a custodian. Sitting above it is a feeder vehicle or special purpose vehicle whose limited partnership interests are represented by digital tokens rather than paper certificates. Investors buy into the feeder; the feeder’s capital flows into the master fund; the master fund makes loans. Apollo’s ACRED share class and KKR’s tokenized feeder both follow this pattern. The token is a claim on the feeder interest, not a synthetic derivative referencing the fund’s performance from a distance — a distinction that matters if the sponsor or the platform ever goes through bankruptcy proceedings, since a direct beneficial interest generally has a cleaner claim than a synthetic wrapper would.
The On-Chain Cap Table and Transfer Restrictions
Once the feeder issues tokens, a transfer agent function is replaced or augmented by a smart contract that maintains the cap table on a permissioned or permissioned-public blockchain. Provenance, the chain used by Figure and Securitize-issued funds, and Centrifuge’s Polkadot-based infrastructure both bake KYC and accreditation checks into the token contract itself: a wallet cannot receive the token unless it has been added to an allowlist after completing subscription documents and investor verification. This is the single biggest misconception about tokenized private credit — the blockchain does not open the fund to the public. It simply moves the compliance check from a manual transfer-agent review to an automated, but still fully gated, smart-contract check. A retail investor without accredited-investor status is blocked from holding the token exactly as they would be blocked from signing the paper subscription agreement.
Distributions work through the same rail. Interest and principal collected from borrowers flow into the master fund, net of fees are calculated at the fund level, and a distribution smart contract (or, in less automated setups, an off-chain process that simply mirrors payments to on-chain wallet addresses) pushes stablecoin or fiat-equivalent payments to each token holder pro rata. Some programs, including several Centrifuge pools built with Anemoy Capital and Janus Henderson, settle these distributions in USDC directly to investor wallets on a monthly cadence, which is faster than the quarterly capital-account statements typical of legacy funds but is not meaningfully different in substance.
NAV, Reporting Cadence, and Why “Real-Time” Is Mostly Marketing
A common claim in tokenized fund marketing is that blockchain rails deliver real-time transparency into fund performance. In practice, the net asset value of a private credit portfolio cannot be computed in real time no matter what ledger records ownership, because the underlying loans are illiquid and require periodic valuation by the manager, often with third-party valuation agent involvement for anything beyond a simple floating-rate senior loan. What tokenization typically delivers is a faster publication cadence for a NAV that is still calculated on a fixed schedule.
Janus Henderson’s Anemoy-managed tokenized Treasury and credit funds on Centrifuge publish NAV daily, which is materially better than the monthly or quarterly cadence of a typical closed-end direct lending vehicle, and it is achievable there because the underlying assets (short-duration government paper and investment-grade credit) are themselves liquid and easy to mark. Direct lending funds holding middle-market senior loans or asset-based finance receivables, by contrast, still mark NAV monthly at best, tokenized or not, because the loans do not trade in a liquid secondary market that would let a pricing service mark them daily with any integrity. Anyone evaluating a tokenized private credit fund should ask precisely how NAV is calculated and by whom, rather than assuming that “on-chain” implies daily or continuous pricing.
The one area where the ledger genuinely changes investor experience is capital account reporting. Traditional LP interests are typically confirmed through PDF capital account statements delivered by a fund administrator 30 to 45 days after quarter-end. A tokenized structure can show an investor their current token balance and historical distribution record in a wallet or a platform dashboard immediately, even while the fund’s official NAV mark still lags by weeks. That is a real convenience improvement, but it should not be confused with intraday price discovery.
Who Is Actually Building This: A Map of the Current Landscape
By mid-2026 the tokenized private credit space has split into two recognizably different camps, and the yield, minimum investment, and liquidity profile differ sharply between them. The table below groups the programs an investor is most likely to encounter.
| Program / Sponsor | Chain / Rail | Underlying Assets | Typical Minimum | Target Net Yield |
|---|---|---|---|---|
| Apollo Diversified Credit (ACRED via Securitize) | Provenance, multi-chain via bridges | Diversified corporate & direct lending | $50,000–$100,000 | ~9%–11% |
| KKR Health Care Strategic Growth (tokenized feeder) | Avalanche subnet via Securitize | Private equity / structured credit hybrid | $20,000–$50,000 | Return profile equity-like, not fixed |
| Figure Technologies / YLDS | Provenance (proprietary) | Home equity lines of credit, consumer receivables | No fixed minimum on some tranches | SOFR-linked, roughly 4%–5% on the registered yield token |
| Centrifuge / Anemoy pools (incl. Janus Henderson JAAA feeder) | Centrifuge (Polkadot-based) & Ethereum | AAA CLO tranches, short-duration credit | $10,000–$25,000 | ~5%–6.5% |
| Maple Finance lending pools | Ethereum, Solana | Overcollateralized crypto-institutional loans, cash management | Often no formal minimum, KYC-gated | ~8%–14% depending on pool risk tier |
Two patterns stand out. First, the Wall Street-sponsored programs (Apollo, KKR, Hamilton Lane) preserve the traditional private credit risk and return profile almost exactly — the innovation is distribution and recordkeeping, not the loans. Second, the crypto-native programs (Maple, Centrifuge outside its institutional TradFi partnerships) tend to price risk differently because their lender base and collateral practices differ from a bank-style credit committee, which is why yields on some Maple pools run well above what a diversified middle-market direct lending fund would ever target. Comparing headline yield across these categories without adjusting for the underlying credit risk is one of the most common analytical errors investors make in this space, and it deserves its own section below.
Secondary Liquidity: The Feature Everyone Advertises and Almost No One Uses
The promise most often attached to tokenized private credit is that a blockchain-native token can trade peer-to-peer, giving investors an exit that a traditional seven-year lockup never offered. The reality in 2026 is that secondary liquidity exists in a narrow, thin form rather than as a continuous market. Securitize operates an SEC-registered alternative trading system, Securitize Markets, where holders of tokens like ACRED can post interest to sell to other qualified investors, and similar functions exist through tZERO and INX. Trading on these venues is order-matching, not continuous quoting: a seller posts an offer, and a trade only executes if a buyer with matching KYC status appears and agrees on price. Volumes across all such venues for private credit tokens remain a small fraction of the primary capital raised into the underlying funds, and most sponsor documents are explicit that there is no guarantee a secondary market will exist at any given time.
Crypto-native pools behave differently but are not necessarily more liquid in a way that helps in a stress scenario. Maple and Centrifuge pools generally let a lender request withdrawal, which is honored out of available cash in the pool rather than through a resale of a token to another buyer. When redemption requests exceed the pool’s cash buffer, withdrawals queue until new deposits or loan repayments replenish liquidity — a mechanism closer to a bank run gate than to selling a stock on an exchange. Several pools imposed multi-week withdrawal queues during 2022’s credit stress and again during isolated 2024 counterparty defaults, which is a useful reminder that a smart contract enforcing a redemption queue is not the same thing as guaranteed liquidity.
The honest framing, and the one worth repeating to any prospective investor, is that a tokenized wrapper can make a future secondary sale operationally easier once a willing buyer exists, but it does not manufacture a willing buyer. Underlying private credit remains illiquid because the loans themselves are illiquid, the investor base is narrow by regulation, and most holders bought the fund for yield rather than for trading. Treat any secondary market access as a option that might be worth something someday, not as a cash-equivalent feature today.
A Worked Example: Modeling Net Yield on a $500,000 Allocation
Numbers make the fee-and-waterfall mechanics concrete. Assume an investor commits $500,000 to a tokenized senior direct lending fund with no fund-level leverage, a gross asset-level yield of 11.8% (a realistic blended coupon across senior secured middle-market loans in 2026), a 1.0% annual management fee on invested capital, a 6% preferred return to the limited partner, and a 15% carried interest to the manager on profits above that preferred return, with a 100% GP catch-up until the split is reached.
Start with gross investment income: $500,000 × 11.8% = $59,000 for the year. Subtract the management fee of 1.0% on the $500,000 commitment, or $5,000, leaving $54,000 available for distribution before any carry is assessed. The preferred return is calculated on the $500,000 base at 6%, which equals $30,000; because the fund cleared that hurdle, the limited partner is guaranteed at least that amount before the manager participates in any upside. The remaining pool available for the carry calculation is $54,000 minus $30,000, or $24,000. Under a 15% carry with full catch-up, the manager takes 15% of that $24,000 remainder, or $3,600, and the limited partner keeps the other $20,400.
Add the limited partner’s two components together: the $30,000 preferred return plus the $20,400 residual share equals $50,400 in total distributions for the year. Divide by the $500,000 commitment and the investor’s net yield comes out to 10.08%, roughly 172 basis points below the 11.8% gross asset yield the underlying loans generated. That gap — management fee plus carried interest — is the price of active origination and underwriting, and it is functionally identical whether the LP interest is a paper certificate or a blockchain token. Tokenization changes none of these mechanics; it only changes how the resulting $50,400 gets reported and paid to the investor’s wallet.
Fee Waterfall on a $500,000 Allocation (Annual)
Bar widths scaled to the $59,000 gross figure. Dashed red marker denotes the preferred-return hurdle line the manager must clear before earning carry.
Reference Table: Traditional vs. Tokenized Private Credit Access
| Feature | Traditional Closed-End Fund | Tokenized Institutional Feeder |
|---|---|---|
| Typical minimum | $5,000,000+ direct; $25,000–$50,000 via feeder or interval fund | $10,000–$100,000, depending on platform and jurisdiction |
| Investor eligibility | Accredited investor or qualified purchaser | Same rules apply; enforced via wallet allowlist instead of manual review |
| Ownership record | Transfer agent ledger, PDF capital account statements | On-chain token balance, wallet-based, real-time balance view |
| NAV cadence | Monthly or quarterly, 30–45 day lag | Same lag for illiquid loans; daily possible only for liquid underlying assets |
| Secondary transfer | Manager consent required, rare, slow paperwork process | Possible via registered ATS, still thin volume and matching-dependent |
| Distribution mechanism | ACH or wire from fund administrator | Stablecoin or fiat rail to wallet, some programs monthly instead of quarterly |
| Fee structure | Management fee + carry, standard | Same, plus occasional platform or custody fee layered on top |
Common Mistakes Investors Make with Tokenized Private Credit
The single most frequent error is treating the word “tokenized” as a synonym for “liquid.” As the sections above lay out, most of these products remain gated by accreditation rules and thin secondary markets; the token is a recordkeeping upgrade, not an exit ramp. Investors who allocate capital assuming they can sell within days if rates move or if they need cash for an emergency are working from marketing copy rather than the actual redemption mechanics in the offering documents.
A second mistake is comparing headline yields across the Wall Street-sponsored and crypto-native categories without adjusting for credit risk and structure. An 11% target on a diversified senior-secured direct lending fund and a 13% yield on a Maple Finance pool lending to crypto-native trading firms are not comparable on an apples-to-apples basis; the collateral, borrower base, and default history behind each number differ enormously, and a higher number on a smaller, newer platform frequently reflects a smaller loss-absorption cushion rather than superior origination skill.
A third mistake is skipping due diligence on the technology layer itself. A tokenized fund introduces smart-contract risk, custody-key risk, and platform operational risk on top of ordinary credit risk. If the platform issuing the token experiences a smart-contract bug, a bridge exploit (relevant for tokens that move across chains via bridging infrastructure), or simply shuts down, investors need to understand whether their legal claim on the underlying fund interest survives independently of the technology platform, or whether the platform is itself a single point of failure. Reputable programs structure the token as a record of a legal interest that exists regardless of the chain’s continued operation, but not every issuer discloses this as clearly as it should.
Fourth, investors sometimes assume tax treatment changes because the interest is represented as a digital token. It generally does not. A tokenized feeder into a US private credit fund typically still generates the same Schedule K-1 or 1099 reporting, ordinary income characterization on interest, and state tax exposure that the equivalent paper LP interest would generate; the wrapper is a technology choice, not a tax election. Treating a token like a crypto asset for tax purposes, when it is legally a security interest in a credit fund, is a preventable and sometimes costly error.
Finally, many investors underweight platform concentration risk. Because a handful of infrastructure providers (Securitize, Provenance, Centrifuge) sit underneath most of the current tokenized private credit market, an operational problem at any one of them has outsized systemic reach across multiple funds from different sponsors that all rely on the same rail.
A Practical Checklist Before You Allocate to a Tokenized Private Credit Fund
- Confirm your accreditation or qualified-purchaser status is verified by the platform before assuming you are eligible, and ask exactly which exemption (Reg D 506(c), Investment Company Act 3(c)(1) or 3(c)(7)) the offering relies on.
- Read the redemption and secondary transfer language in the actual offering memorandum, not the marketing page, and ask the sponsor for real historical data on secondary trading volume if any exists.
- Separate the credit story from the technology story: evaluate the underlying loan book, borrower concentration, and historical loss rate exactly as you would for a non-tokenized fund.
- Ask who calculates NAV, on what schedule, and whether a third-party valuation agent is involved for anything beyond simple floating-rate paper.
- Understand custody: does the platform custody the token in an omnibus wallet, or do you hold a private key directly, and what happens to your claim if the platform itself fails?
- Get a plain answer on tax reporting format (K-1 vs 1099) before committing capital, and confirm whether the fund files in your state of residence.
- Check whether the fee schedule includes a platform or technology fee layered on top of the standard management fee and carry.
- Model your net yield using the actual waterfall terms in the documents, the way the worked example above does, rather than relying on a single headline “target yield” figure.
Key Takeaways
- Tokenized private credit funds replace paper cap tables and transfer agent processes with blockchain-recorded ownership; the loans, fees, and accreditation requirements underneath are largely unchanged.
- Institutional sponsors including Apollo, KKR, and Hamilton Lane have tokenized feeder access to existing funds, typically lowering minimums to roughly $20,000–$100,000 while keeping the same eligibility rules.
- Crypto-native platforms like Maple Finance and Centrifuge originate or fund loans directly through on-chain pools, with a materially different risk and liquidity profile than a Wall Street-sponsored feeder.
- Secondary liquidity exists through registered venues such as Securitize Markets, but volume remains thin; a token does not guarantee a buyer will appear.
- Net yield to the investor is shaped by the same management fee and carried interest mechanics as any traditional private credit fund, as the worked $500,000 example above demonstrates.
- Tax treatment, custody structure, and platform concentration risk deserve as much diligence as the credit quality of the underlying loans.
Frequently Asked Questions
What exactly gets tokenized in a “tokenized private credit fund”?
The ownership record of an investor’s stake in a feeder vehicle or special purpose vehicle gets tokenized, not the underlying loans themselves. The token represents a beneficial interest in that feeder, which in turn holds an interest in the master fund that actually makes the loans.
Are tokenized private credit funds open to non-accredited investors?
Almost never in their current form. The vast majority of programs rely on the same accredited-investor or qualified-purchaser exemptions that traditional private funds use, and the blockchain simply automates the KYC and eligibility check through a wallet allowlist rather than removing it.
Does tokenization make private credit fund investments liquid?
Not in any meaningful sense today. A handful of registered alternative trading systems allow token holders to post interest to sell, but trading volume is thin and there is no guarantee a buyer will be available at any given time, so investors should still plan for a multi-year holding period.
How is a tokenized private credit fund different from a crypto lending pool like Maple or Centrifuge?
Institutional tokenized feeders wrap an existing, traditionally underwritten private credit fund; crypto-native pools originate or fund loans directly on-chain, often to crypto-native borrowers or through different collateral arrangements, and typically carry a different risk and yield profile than a diversified middle-market direct lending fund.
What happens to my token if the underlying fund manager fails or the blockchain has an outage?
In well-structured programs the token represents a legal beneficial interest in the fund that exists independently of the blockchain’s continued operation, so the underlying claim should survive a technology outage, though investors should confirm this explicitly in the offering documents rather than assuming it.
How are yields on tokenized private credit funds taxed?
Generally the same way as the equivalent non-tokenized fund interest would be taxed, commonly as ordinary income reported on a Schedule K-1 or 1099 depending on the fund’s structure; the token wrapper is a recordkeeping technology, not a change in tax character.
References
- U.S. Securities and Exchange Commission, Regulation D exemption framework and accredited investor definitions (Rule 501 of Regulation D).
- Investment Company Act of 1940, Sections 3(c)(1) and 3(c)(7) private fund exemptions.
- Public sponsor disclosures and press materials from Apollo Global Management, KKR, and Hamilton Lane regarding tokenized feeder launches via Securitize on the Provenance and Avalanche networks, 2025.
- Figure Technologies public disclosures on Provenance Blockchain loan originations and the YLDS registered yield token.
- Centrifuge and Anemoy Capital public program documentation on tokenized short-duration credit pools, including the Janus Henderson-associated feeder.
- Maple Finance public pool documentation and historical withdrawal-queue disclosures.
None of the above is investment, legal, or tax advice. Private credit, tokenized or not, involves real risk of loss, illiquidity, and manager-specific credit outcomes; anyone considering an allocation should review the actual offering documents and consult a licensed advisor before committing capital. For a broader primer on how real-world assets move on-chain in the first place, see our complete guide to real-world asset tokenization, which covers the mechanics this article builds on.