Quick answer
A well-scoped smart building retrofit — building management system (BMS) upgrades, IoT sensor networks, fault detection and diagnostics (FDD), and LED-plus-controls lighting — typically costs $3 to $6 per square foot and cuts whole-building energy consumption by 15% to 28%. On a 250,000 square foot office asset, that usually produces a simple payback of four to six years and, once the energy savings are capitalized at a market cap rate, a jump in asset value that runs two to four times the retrofit’s own price tag. The math works because operating expense reductions flow straight into net operating income, and NOI is the number buyers actually pay a multiple for.
Ask a facilities director in 2021 what a “smart building” meant and you’d likely get a shrug and a mention of a fancy thermostat app. Ask the same question today inside a REIT’s asset management team and the answer looks entirely different: a layered stack of sensors, analytics software, and automated controls that turns a passive concrete-and-glass structure into something closer to a continuously optimized machine. The shift didn’t happen because building owners suddenly fell in love with technology. It happened because three forces converged at once — utility costs that no longer behave the way they did a decade ago, municipal carbon laws with real financial teeth, and a capital markets environment where lenders and appraisers have started pricing energy performance directly into valuations.
Why Smart Retrofit Economics Changed in the Last Few Years
Commercial buildings consume roughly 35% of electricity generated in most major U.S. metro areas, and in dense urban cores that figure climbs higher because building stock skews toward older, less efficient construction. For most of the last thirty years, the response to rising utility bills was incremental: swap a chiller when it dies, upgrade lighting during a routine capital cycle, maybe add a programmable thermostat. None of that required rethinking how a building actually operates minute to minute.
Three things broke that pattern. First, commercial electricity rates in gateway markets rose faster than general inflation for several consecutive years, driven by grid modernization surcharges and demand-charge structures that punish buildings for uncontrolled peak usage — exactly the kind of waste a smart control system is built to eliminate. Second, a wave of building performance ordinances, led by New York’s Local Law 97 and mirrored in Boston, Washington D.C., St. Louis, and a growing list of cities under the broader BERDO and building performance standard umbrella, now attach direct financial penalties to carbon emissions above a declining cap. These aren’t abstract sustainability targets; they’re annual fines calculated per metric ton of CO2 equivalent, and the caps get tighter on a fixed schedule through 2030 and beyond. Third, and this is the part that changed owner behavior the fastest, institutional lenders and appraisers began treating energy performance data as an underwriting input rather than a marketing footnote. A building with a poor ENERGY STAR score or an unresolved compliance exposure now gets a harder look during refinancing, and in some cases a measurably higher spread.
Put those together and a retrofit that used to be a discretionary sustainability initiative becomes a defensive financial necessity with a calculable return. The interesting part, and the reason this topic deserves more than a surface pass, is that the retrofit category itself has fragmented into distinct tiers with very different cost structures, paybacks, and risk profiles. Treating “smart building retrofit” as one monolithic decision is the single most common mistake owners make, and it’s usually what turns a good idea into a disappointing project.
The Technology Stack: What Actually Gets Installed
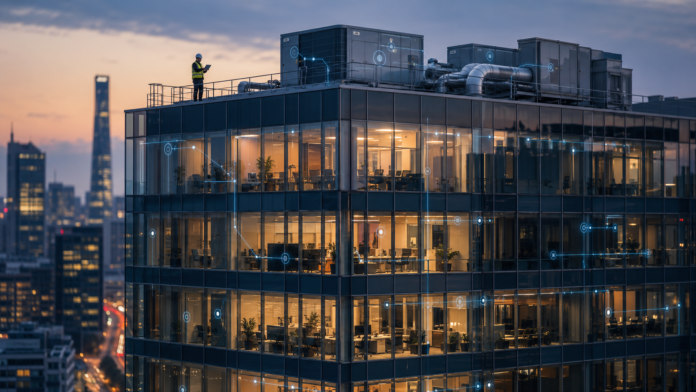
A smart building retrofit is not one product. It is a layered set of systems that talk to each other, and the ROI depends heavily on which layers you install and in what sequence.
Building Management System (BMS) Modernization
The BMS is the central nervous system — the software and controller network that governs HVAC, lighting zones, and life-safety interfaces. Many buildings built or last renovated before the mid-2010s run on proprietary, closed-protocol controllers that can’t easily exchange data with modern analytics platforms. Modernizing to an open protocol (BACnet or similar) is often the unglamorous first step that everything else depends on, and skipping it is why some retrofits underperform their projected savings by a wide margin.
IoT Sensor Networks and Sub-Metering
Wireless occupancy sensors, CO2 sensors, and zone-level temperature sensors feed granular, real-time data into the BMS instead of relying on a handful of thermostats to represent an entire floor. Sub-metering breaks a single utility bill down by floor, tenant, or system, which matters enormously for retrofit financing because you can no longer prove savings against a single blended number — you need to isolate which system change produced which reduction.
Fault Detection and Diagnostics (FDD)
This is the layer that produces the most underappreciated savings. FDD software continuously compares actual equipment behavior against expected performance curves and flags anomalies — a valve stuck open, a damper cycling incorrectly, an economizer that never engages during mild weather. Studies from national labs studying commercial HVAC fleets have repeatedly found that this kind of “soft fault” waste, invisible without continuous monitoring, commonly accounts for 10% to 20% of total HVAC energy use in buildings that have never had FDD deployed.
Lighting Retrofits and Daylight Harvesting
LED conversion paired with occupancy and daylight sensors remains the fastest-payback component of almost any retrofit, often under three years on its own, because it combines a large wattage reduction with minimal disruption to tenants. It’s rarely the biggest dollar-value saver in a large office building, but it is usually the piece that gets financed first because the payback is so short it de-risks the rest of the project for a skeptical finance committee.
The Financial Mechanics: How Energy Savings Become Asset Value
This is the part that gets glossed over in most retrofit pitches, and it’s the actual reason institutional owners care. A dollar saved on utility expense is not just a dollar saved — in an income-producing property, it is a dollar added to net operating income, and NOI is the figure that gets capitalized into value.
The relationship is simple algebra: Value = NOI ÷ Cap Rate. If a retrofit reduces annual operating expenses by $200,000 and the asset trades in a market where similar buildings sell at a 6% capitalization rate, that $200,000 in recurring savings is worth roughly $3.33 million in asset value — not $200,000. This is the leverage effect that makes smart retrofits attractive to owners who might otherwise dismiss a six-figure capital outlay: the retrofit cost is a one-time expense, but the NOI improvement is capitalized in perpetuity by whoever eventually buys or refinances the building.
There’s a second, quieter mechanic at work too. Buildings that can document verified energy performance data increasingly qualify for green-labeled loan products with modestly lower interest rates, and appraisers in several major markets have begun applying explicit valuation premiums, sometimes cited in the 4% to 8% range for like-for-like comparables, to certified or high-performing assets. Neither of those effects shows up in a simple utility bill comparison, but both show up on a balance sheet.
Compliance-Driven ROI: When the Retrofit Isn’t Optional
For a growing share of the commercial building stock, the retrofit decision isn’t really a choice anymore — it’s a question of how to comply at the lowest cost. New York City’s Local Law 97 is the sharpest example: buildings over 25,000 square feet face annual carbon caps, and non-compliance triggers penalties of $268 per metric ton of CO2 equivalent above the limit, with the caps tightening substantially for the 2030 compliance period. A mid-size commercial building that exceeds its cap by even a modest margin can face six-figure annual fines that recur every year until the building is brought into compliance.
Boston’s BERDO 2.0, Washington D.C.’s Building Energy Performance Standards, and similar ordinances in St. Louis, Denver, and a growing list of jurisdictions follow the same basic template: benchmark, cap, penalize, and tighten the cap over time. Owners in these markets face a straightforward comparison — pay the recurring fine indefinitely, or spend once on a retrofit that eliminates the exposure and simultaneously reduces the underlying utility bill. Framed that way, the “cost” of a retrofit is more accurately described as the cost of avoiding a permanent, compounding liability, which is a very different capital allocation conversation than a discretionary upgrade.
This compliance dimension has also reshaped how the retrofit market interacts with the rest of institutional real estate. The same pressure toward density, efficiency, and defensible ESG credentials that has pushed institutional capital into vertically integrated, high-density urban assets is pushing existing owners to retrofit rather than let older stock become structurally uncompetitive. A building that can’t credibly solve its emissions exposure risks becoming what appraisers now informally call a “stranded asset” — one that can still collect rent today but faces a shrinking pool of buyers and lenders willing to underwrite it five years out.
Financing the Retrofit: PACE, Green Loans, and the 179D Deduction
Retrofit projects rarely get funded purely out of operating cash flow, and the financing structure often matters as much as the technology choice. Commercial Property Assessed Clean Energy (PACE) financing has become one of the more common vehicles specifically because it’s structured as a property tax assessment rather than a conventional loan — it stays with the property through a sale, runs for terms up to 20 to 25 years, and in most structures sits outside typical loan-to-value covenants, which means it doesn’t compete with a building’s existing mortgage for balance sheet capacity.
On the tax side, the federal Section 179D deduction has become significantly more valuable following recent updates: qualifying commercial building energy efficiency improvements can generate a deduction scaling up with the percentage of energy savings achieved, reaching figures in the range of $5.65 per square foot for 2025 placed-in-service projects that meet prevailing wage and apprenticeship requirements and hit the top efficiency tier. For a 250,000 square foot building, that ceiling alone represents over $1.4 million in potential deduction value, which can materially shorten the after-tax payback period compared to the raw pre-tax calculation most feasibility studies lead with.
Utility rebate programs, though smaller in dollar terms, are worth stacking on top of PACE and 179D because they typically apply to specific equipment categories — LED fixtures, VFDs, high-efficiency chillers — and can offset 10% to 30% of that specific line item’s cost without affecting eligibility for the other two programs.
Worked Example: A 250,000 Square Foot Office Retrofit
Numbers make this concrete. Consider a Class B office building of 250,000 rentable square feet, built in 1998, with a baseline annual energy spend of $2.85 per square foot, or $712,500 per year.
The owner commissions a Tier 2 retrofit — BMS modernization to an open protocol, an FDD layer across the HVAC fleet, full LED conversion with daylight and occupancy sensors, and floor-level sub-metering — at a cost of $3.50 per square foot, or $875,000 total.
Annual energy cost: before vs. after retrofit
Baseline
Post-retrofit
A 24% reduction in energy consumption removes $171,000 from the annual utility line, and predictive maintenance from the FDD layer trims a further $37,500 in avoided service calls and extended equipment life, for a combined annual operating expense reduction of $208,500.
Set against the $875,000 project cost, the simple payback lands at roughly 4.2 years — before factoring in any 179D deduction or utility rebate, both of which would shorten it further. But the payback period isn’t the number that matters most to the owner planning a sale or refinance in three to five years. Capitalized at a 6% market cap rate, the $208,500 annual NOI improvement adds approximately $3.48 million in asset value. Against the $875,000 spent, that’s roughly a 3.97x multiple of value created per dollar invested — a return profile that few other capital improvements in a building’s lifecycle can match, because most capital projects (a new roof, an elevator modernization) preserve value rather than creating it.
If the same building instead financed the project through a 20-year PACE assessment at a 6.25% rate, annual debt service would run approximately $76,700 — well below the $208,500 in annual savings, meaning the retrofit is cash-flow positive from year one, before any tax benefit is applied. That combination, positive day-one cash flow plus a multi-million-dollar valuation uplift, is the specific mechanism that has pulled smart retrofits out of the “nice to have” category and into standard institutional underwriting.
Comparing Retrofit Tiers: Cost, Savings, and Payback
Not every building needs, or can justify, the same scope. The table below reflects typical ranges observed across commercial office and mixed-use retrofit projects in major U.S. metros.
| Retrofit tier | Typical scope | Cost per sq ft | Energy savings | Simple payback |
|---|---|---|---|---|
| Tier 1: Sensors & controls | Occupancy/daylight sensors, LED conversion, basic scheduling | $1.50 – $2.50 | 8% – 14% | 2 – 3 years |
| Tier 2: BMS + FDD + lighting | Open-protocol BMS, fault detection, sub-metering, full lighting | $3.00 – $5.50 | 15% – 28% | 4 – 6 years |
| Tier 3: Deep retrofit | Tier 2 plus HVAC equipment replacement, envelope, electrification | $15 – $35 | 35% – 55% | 9 – 15 years |
The tier choice should be driven by the compliance timeline as much as by capital availability. A building facing a Local Law 97-style penalty in the near term but with equipment that still has ten years of useful life left is usually better served by Tier 2 — fast enough to close the compliance gap without committing to equipment replacement before it’s actuarially necessary. Tier 3 tends to make sense only when major mechanical equipment is already near end-of-life and would need capital regardless.
Common Mistakes Owners Make
The gap between projected and actual retrofit savings is usually explained by a handful of recurring errors rather than bad luck or faulty technology.
- Skipping the BMS modernization and bolting sensors onto a closed-protocol system. The sensors generate data that the underlying controls can’t act on automatically, so savings depend on manual intervention that rarely happens consistently.
- Measuring against a stale baseline. If the baseline year included an unusually mild winter or a period of low occupancy, the “savings” reported in year one can be partly an artifact of weather or occupancy normalization rather than the retrofit itself. Serious projects normalize against weather data and occupancy schedules, not just the prior year’s raw bill.
- Underinvesting in commissioning. A retrofit that is installed but never properly commissioned and tuned commonly captures only 50% to 70% of its modeled savings during the first year, because default control sequences rarely match the specific building’s actual usage patterns out of the box.
- Ignoring tenant behavior and lease structure. In buildings with triple-net leases where tenants pay their own utilities directly, the landlord captures compliance benefits but none of the direct utility savings, which changes the ROI calculation and financing approach substantially.
- Treating the retrofit as a one-time project instead of an ongoing program. FDD and analytics platforms degrade in value if nobody reviews the alerts. Buildings that assign an actual owner to the dashboard sustain savings for years; buildings that don’t tend to drift back toward baseline performance within 18 to 24 months.
Practical Checklist Before You Commit Capital
- Pull twelve to twenty-four months of interval utility data and normalize it for weather and occupancy before setting a baseline.
- Confirm your BMS protocol is open or can be bridged; budget for modernization if it isn’t.
- Run the compliance math first — calculate your projected Local Law 97 or equivalent penalty exposure through 2030 before sizing the retrofit tier.
- Model the NOI-to-value uplift using your market’s actual cap rate, not a national average.
- Get a written 179D eligibility estimate from a qualified engineer before assuming the top-tier deduction applies.
- Compare PACE, green loan, and utility rebate structures side by side on after-tax cash flow, not just headline interest rate.
- Build a minimum twelve-month commissioning and tuning period into the project timeline, not just the installation schedule.
- Assign a named internal owner for the FDD dashboard before the system goes live.
Key Takeaways
- Smart building retrofit ROI is driven less by the technology itself and more by how energy savings convert into net operating income and, through the cap rate, into asset value.
- Tier 2 retrofits (BMS, FDD, sub-metering, lighting) offer the strongest balance of cost, savings, and payback for most existing commercial buildings.
- Local carbon compliance ordinances have turned many retrofits from optional upgrades into defensive necessities with a clear cost of inaction.
- PACE financing and the 179D deduction can each materially shorten payback, and stacking both is common in well-structured projects.
- Commissioning and ongoing dashboard ownership determine whether projected savings actually materialize in year one and persist over time.
Frequently Asked Questions
What is a realistic payback period for a smart building retrofit?
Most Tier 2 retrofits combining BMS modernization, fault detection, sub-metering, and LED lighting pay back in four to six years on energy savings alone. Lighting-only projects can pay back in two to three years, while deep retrofits involving HVAC equipment replacement typically take nine to fifteen years.
How does a smart building retrofit affect property value, not just utility bills?
Energy savings reduce operating expenses, which increases net operating income. Because commercial real estate is valued by dividing NOI by a market capitalization rate, even a modest annual savings figure can translate into a valuation increase several times larger than the retrofit’s own cost.
Do smart building retrofits help with local carbon emissions laws like Local Law 97?
Yes. Ordinances such as New York’s Local Law 97 impose annual per-ton penalties on buildings that exceed carbon caps, and those caps tighten over time. A retrofit that reduces energy consumption directly reduces the carbon calculation used to determine compliance, often eliminating or substantially reducing penalty exposure.
What financing options exist specifically for smart building retrofits?
Commercial PACE financing, structured as a property tax assessment rather than a conventional loan, is one of the most common vehicles because it can run 20 or more years and typically doesn’t count against existing loan covenants. The federal Section 179D deduction and utility-specific rebate programs are commonly layered on top of PACE or a green loan to further improve after-tax returns.
Why do some smart building retrofits underperform their projected savings?
The most frequent causes are installing sensors on top of an outdated, closed-protocol control system that can’t act on the new data automatically, using an unnormalized baseline that flatters or understates true performance, and skipping proper commissioning, which typically leaves 30% or more of modeled savings uncaptured in the first year.
References
- U.S. Energy Information Administration, Commercial Buildings Energy Consumption Survey (CBECS) data on commercial sector electricity use.
- NYC Mayor’s Office of Climate and Environmental Justice, Local Law 97 compliance and penalty structure documentation.
- U.S. Department of Energy, Federal Energy Management Program guidance on fault detection and diagnostics for commercial HVAC systems.
- Internal Revenue Service, Section 179D Commercial Buildings Energy-Efficient Tax Deduction guidance, including prevailing wage and apprenticeship provisions.
- PACENation, Commercial Property Assessed Clean Energy (C-PACE) program structure and state authorization data.
- ENERGY STAR Portfolio Manager, technical reference for benchmarking commercial building energy performance.
- Boston Building Emissions Reduction and Disclosure Ordinance (BERDO 2.0), City of Boston Environment Department.