The short answer: when a small cluster of mega-cap stocks drives most of the market’s return, cap-weighted funds win on paper because they simply own more of what’s winning. When the rally broadens out to mid-caps, smaller names, and unloved sectors, equal-weight funds tend to catch up and often pull ahead. Neither approach is “correct” in isolation — the right pick depends on how concentrated you think the market will stay, how much turnover and tax drag you can tolerate, and whether you want your portfolio’s fate tied to a handful of giant companies or spread more evenly across the index.
Every few years, a small group of enormous companies starts to account for an outsized share of a major index’s total value. That is exactly the setup investors are wrestling with now, and it has revived a debate that dates back to the 1970s: should you own a benchmark that lets the biggest winners dominate, or one that treats every company in the index as equally important? This piece walks through both approaches, shows how they behave differently depending on whether mega-caps or the broader market are doing the heavy lifting, and lays out the turnover, tax, and suitability trade-offs that rarely make it into a fund fact sheet.
Two Ways to Build the Same Index
Start with a basic truth: an equal-weight fund and a cap-weighted fund tracking the identical 500 companies can post wildly different returns in the same calendar year. They hold the same stocks. They just decide, in fundamentally different ways, how much of each stock to hold.
Cap-Weighting: Let Size Decide
A traditional cap-weighted index — the kind most people mean when they say “S&P 500 fund” — sizes each holding according to the company’s total market value relative to the index as a whole. If one company is worth $3 trillion and the entire index is worth $50 trillion, that company gets roughly a 6% slice of the fund, dollar for dollar. As a stock’s price rises, its weight in the fund automatically climbs too, with no buying or selling required. The fund’s return becomes a size-weighted average of every holding’s return, which means the largest handful of companies can end up driving the majority of the index’s total gain or loss in any given period.
Equal-Weighting: Let the Roster Decide
An equal-weight fund throws out market value as the sizing rule and instead gives every constituent close to the same slice of the portfolio. In a 500-stock index, that means each holding starts near 0.2% of assets, whether the company is worth $3 trillion or $8 billion. Because prices drift apart from each other constantly, the fund has to be periodically rebalanced — trimming the winners and topping up the laggards — to pull every position back toward that same 0.2% target. The fund’s return becomes a straight average of all 500 stocks’ returns, with no single company able to dominate the outcome no matter how large it grows.
That single structural difference — automatic size-based weighting versus periodic forced rebalancing back to parity — explains almost everything else in this comparison: the performance gaps, the turnover, the tax bills, and the kind of investor each approach tends to suit.
Historical Performance Divergence: Who Wins Depends on Who’s Driving the Bus
The single biggest driver of the gap between equal-weight and cap-weight returns is market breadth — how many stocks are actually participating in a rally versus how concentrated the gains are in a handful of names.
When a small set of mega-cap companies posts outsized earnings growth and investor enthusiasm concentrates around them — think a dominant theme like cloud computing, e-commerce, or an emerging technology cycle — a cap-weighted fund captures that enthusiasm directly and immediately, because those same companies already carry the largest weights. An equal-weight fund, by contrast, gives each of those same companies only a tiny sliver of the portfolio, so their gains get diluted across hundreds of smaller positions that may be moving sideways or down. In these stretches, cap-weighted funds have historically pulled meaningfully ahead of their equal-weight counterparts, sometimes by several percentage points in a single year.
The pattern flips when leadership broadens. Once the rally (or the recovery) spreads beyond the largest names into mid-caps, cyclicals, financials, and smaller companies across the index, the equal-weight fund’s structural tilt toward smaller, more numerous positions starts paying off. Academic work on size and value factors has long shown that smaller companies, averaged over long stretches, have delivered a return premium over the very largest names — a pattern equal-weight strategies harvest almost automatically, simply by holding every company at the same size rather than letting a few giants crowd out the rest.
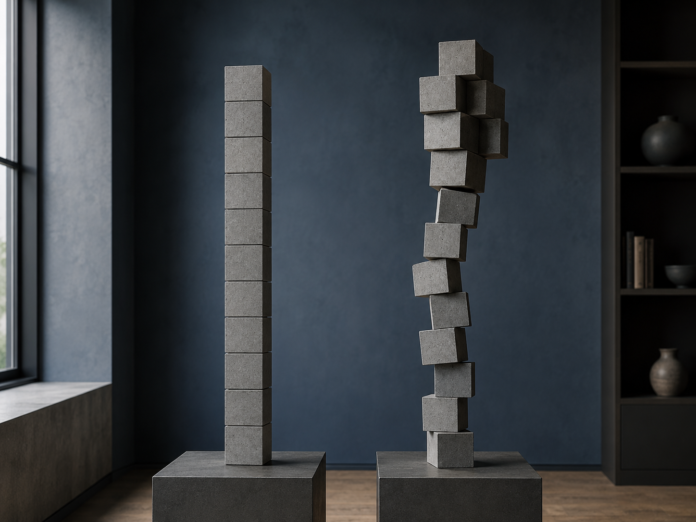
What that chart illustrates is the mechanical root of the performance divergence. In a cap-weighted fund, the ten biggest companies can carry roughly two-fifths of the entire portfolio’s fate. In an equal-weight version of the same index, those same ten companies carry only about a fiftieth of the outcome. Whichever group — the giants or everybody else — performs best in a given stretch determines which structure wins, and the gap between the two can widen or narrow sharply depending on where we are in that cycle.
Rebalancing Frequency, Turnover, and the Tax Bill
Beyond performance, the two approaches diverge sharply in how much trading they require, and trading has a cost that shows up whether or not the fund itself is “cheap” on an expense-ratio basis.
A cap-weighted fund is close to self-maintaining. Because weights adjust automatically as prices move, the fund only needs to trade when a company is added to or removed from the index, or when share counts change due to buybacks, secondary offerings, or corporate actions. Annual turnover on a plain cap-weighted S&P 500 fund typically runs in the low single digits — often somewhere between 2% and 5% of assets in a given year.
An equal-weight fund is built around the opposite premise. Every quarter, the fund provider resets every position back to its target share, which means systematically selling the names that ran up and buying more of the names that lagged. That is a disciplined, rules-based form of contrarian rebalancing, and it is also a meaningful amount of trading activity, repeated four times a year, across hundreds of positions. Annual turnover on equal-weight index products commonly lands in the 20% to 30% range, and can run higher in especially volatile years.
Inside a tax-advantaged account — a 401(k), an IRA, or similar — this difference barely matters. Trading inside the fund does not trigger a personal tax bill in those wrappers. Inside a regular taxable brokerage account, it matters a great deal. Higher turnover inside a fund tends to generate more realized capital gains that get distributed to shareholders each year, typically in December, and those distributions are taxable in the year they’re paid even if you never sold a share yourself. An equal-weight fund’s constant trimming and topping-up produces a steady drip of these distributions; a cap-weighted fund’s minimal trading keeps distributions comparatively rare and small. Investors holding either fund in a brokerage account should check the fund’s historical capital gains distribution record before assuming the lower expense ratio tells the whole cost story.
Sector Exposure and the Concentration You’re Actually Buying
The weighting method also quietly rewrites the sector map underneath the fund. A cap-weighted index will lean hard into whichever sector happens to house the largest companies at any given time. When technology and communication-services giants dominate the largest-company list, a cap-weighted fund can end up with a third or more of its assets tied to that single sector, regardless of how the fund’s marketing describes it as “broadly diversified.”
An equal-weight version of the same index tells a different story. Because every company gets the same dollar allocation, sector weight in an equal-weight fund is driven by how many companies from that sector sit in the index, not by how large those companies happen to be. A sector with 60 mid-sized constituents and a sector with 20 giant constituents can end up looking far more comparable in an equal-weight fund than they do in the cap-weighted version, where the giants’ sheer size swamps the count. This tends to pull an equal-weight fund’s sector mix toward industrials, financials, materials, and other sectors that have many members but few true mega-caps, while trimming its exposure to whichever sector currently houses the largest companies.
Neither sector profile is inherently safer. A cap-weighted fund’s sector concentration is a bet — often an unintentional one — that the current market leaders keep leading. An equal-weight fund’s more even sector spread reduces that single-sector dependency but increases exposure to smaller, sometimes more cyclical companies that can be more volatile individually, even if the fund as a whole ends up less concentrated.
Head-to-Head: The Full Comparison
| Criterion | Cap-Weighted | Equal-Weight |
|---|---|---|
| Weighting logic | By market value; largest companies get the largest share | Every company gets roughly the same share |
| Rebalancing | Mostly automatic via price moves; trades only on index changes | Manual reset to equal weights, typically quarterly |
| Typical annual turnover | 2%–5% | 20%–30% |
| Taxable-account friction | Low — infrequent, small capital gains distributions | Higher — quarterly trimming realizes gains regularly |
| Behavior in mega-cap-led rallies | Tends to outperform — captures winners at full weight | Tends to lag — winners diluted across many positions |
| Behavior in broad-market rallies | Tends to lag — smaller gainers barely move the needle | Tends to outperform — every gainer counts equally |
| Sector exposure | Skews toward sectors housing the largest companies | Skews toward sectors with the most constituents |
| Single-stock concentration risk | Higher — top holdings can approach 35%–40% combined | Low — no holding meaningfully larger than another |
| Typical expense ratio | Very low, often under 0.05% | Modestly higher, commonly 0.20%–0.40% |
A Worked Example: The Same $50,000, Two Different Outcomes
Numbers make the mechanics easier to see than a table alone. Picture two investors, each putting $50,000 into a fund tracking the same 500-company index on the same day — one in the cap-weighted version, one in the equal-weight version.
In year one, a small handful of mega-cap technology companies post enormous earnings growth and their share prices climb sharply, while the other 490-odd companies in the index post modest, unremarkable gains in the mid single digits. Because those mega-caps already carry a combined weight near 35% of the cap-weighted fund, their surge lifts the whole cap-weighted portfolio to a 22% return for the year. The equal-weight investor, holding those same mega-caps at roughly 0.2% each instead of a combined 35%, sees far less benefit from their run — the equal-weight fund finishes the year up 11%, roughly half the cap-weighted gain, purely because of how the same set of returns got distributed across the portfolio.
In year two, sentiment shifts. The mega-caps stall out and trade roughly flat, while a broad recovery lifts financials, industrials, energy, and smaller companies across the index, many of them posting double-digit gains. The cap-weighted fund, still anchored by its flat mega-cap core, manages only a 6% return. The equal-weight fund, having spent the quiet part of year one buying more of those same laggards during its rebalancing, is now fully exposed to their year-two recovery and returns 15%.
Over the two years combined, the cap-weighted investor is up roughly 29% cumulatively; the equal-weight investor is up roughly 27.6% cumulatively — remarkably close, despite wildly different paths in each individual year. That closeness is the point. Over a full cycle that includes both a concentrated rally and a broadening recovery, the two approaches often land closer together than the headline year-by-year gaps suggest. The real-world difference shows up less in the destination and more in how bumpy, and how tax-inefficient, the ride was to get there — plus how many nerve-wracking months you spent watching one approach badly trail the other before the cycle turned.
When Cap-Weight Wins, and When Equal-Weight Wins
Cap-weighting tends to be the stronger choice for an investor who believes market leadership will stay concentrated for a while longer, who wants to minimize trading costs and tax drag inside a taxable account, and who is comfortable letting the fund’s largest holdings essentially set the tone for the whole portfolio. It also suits investors prioritizing rock-bottom expense ratios and simplicity, since cap-weighted products are the default, most heavily traded, and typically cheapest version of any given index.
Equal-weighting tends to suit an investor who is uneasy with how much of a “diversified” fund’s return now hinges on a small cluster of giant companies, who has a long enough time horizon to sit through stretches of relative underperformance while waiting for market breadth to return, and who is holding the position inside a tax-advantaged account where the extra turnover doesn’t translate into an annual tax bill. It also appeals to investors who specifically want a contrarian, mean-reversion-style tilt built into their core holding — buying low and trimming high on a disciplined schedule, without having to make that call themselves.
A middle path many investors land on is holding a cap-weighted fund as the core position and layering a smaller equal-weight allocation on top, deliberately diluting concentration risk without fully abandoning the low-cost, low-turnover benefits of the cap-weighted structure. That blended approach also sidesteps the all-or-nothing bet on which regime — mega-cap-led or broad-based — plays out next.
Common Mistakes Investors Make With This Decision
- Judging the choice off a single year’s return. One strong or weak year tells you almost nothing about which weighting scheme is structurally better suited to your goals; it mostly tells you which regime the market happened to be in.
- Holding an equal-weight fund in a taxable account without checking the distribution history. The quarterly rebalancing that makes equal-weight funds work also generates capital gains distributions that arrive whether or not you wanted the tax event that year.
- Assuming equal-weight funds are automatically “safer.” They remove single-stock concentration risk but typically carry more exposure to smaller, more cyclical companies, which can mean sharper individual-stock swings even as the aggregate portfolio looks more balanced on paper.
- Doubling up on mega-cap exposure without realizing it. An investor holding a cap-weighted S&P 500 fund alongside several individual mega-cap stocks, or a separate technology-sector fund, can end up with far more concentration than the headline “diversified index fund” label suggests.
- Chasing the weighting scheme that just won. Switching into equal-weight right after it outperformed, or back into cap-weight right after a mega-cap-led surge, tends to buy in near the top of whichever cycle is already ending.
A Practical Checklist Before You Choose
- Check what share of the cap-weighted version of your target index sits in its ten largest holdings — if that number feels uncomfortably high, an equal-weight tilt may address the specific concern you have.
- Decide which account the position will live in; save the higher-turnover equal-weight structure for tax-advantaged accounts where possible.
- Compare expense ratios side by side — the equal-weight premium is usually modest, but it compounds over decades and should be a conscious trade-off, not an accident.
- Look at the fund’s actual historical capital gains distributions, not just its expense ratio, before assuming you know its true annual cost in a taxable account.
- Decide upfront how long you’re willing to underperform the other approach during whichever regime doesn’t favor your choice, since both approaches go through multi-year stretches of relative disappointment.
- Consider a blended allocation if you can’t comfortably commit to one regime persisting — a partial equal-weight sleeve alongside a cap-weighted core reduces the all-or-nothing nature of the bet.
Key Takeaways
- Cap-weighted funds size holdings by market value, so a handful of mega-cap companies can end up driving most of the fund’s return; equal-weight funds size every holding roughly the same, spreading that influence across the entire roster.
- When mega-caps lead the market, cap-weighted funds tend to win; when the rally broadens to the rest of the index, equal-weight funds tend to catch up or pull ahead.
- Equal-weight funds require regular rebalancing — commonly quarterly — which drives turnover roughly five to ten times higher than a typical cap-weighted fund.
- That higher turnover matters most in taxable accounts, where it tends to generate larger and more frequent capital gains distributions.
- Sector exposure differs meaningfully between the two structures: cap-weight tilts toward whichever sector houses the biggest companies, while equal-weight tilts toward whichever sector has the most constituents.
- Neither approach is universally superior; the decision hinges on your view of market breadth, your account type, your cost sensitivity, and your tolerance for multi-year stretches of relative underperformance.
Frequently Asked Questions
Is an equal-weight fund riskier than a cap-weighted fund?
It depends on how you define risk. An equal-weight fund removes the concentration risk of a handful of giant companies dominating the portfolio, which many investors consider a meaningful risk reduction. At the same time, it typically holds more exposure to smaller, more volatile companies on an individual-stock basis, so its day-to-day swings can feel choppier even though its overall concentration is lower.
Why does an equal-weight fund need to be rebalanced so often?
Stock prices drift apart from each other continuously, so a portfolio that started with every holding at the same weight quickly stops being equal as some stocks rise faster than others. Quarterly rebalancing resets every position back toward its target share, which is also why equal-weight funds carry noticeably higher turnover than cap-weighted funds.
Does higher turnover in an equal-weight fund always mean a bigger tax bill?
Not always, but it raises the odds. Higher turnover tends to generate more realized capital gains inside the fund, which get passed through to shareholders as taxable distributions in a regular brokerage account. Inside a 401(k), IRA, or similar tax-advantaged account, that turnover has no direct tax consequence for the investor.
Can I just hold both an equal-weight fund and a cap-weighted fund at the same time?
Yes, and many investors do exactly that as a way to dial concentration risk up or down without making an all-or-nothing bet. A common approach is holding a cap-weighted fund as the core position and adding a smaller equal-weight allocation on top to reduce single-stock concentration while keeping most of the portfolio in the lower-cost, lower-turnover structure.
Which approach has performed better over the long run?
Over long, multi-decade stretches that include both concentrated and broad-based market regimes, the two approaches have often produced fairly similar cumulative returns, even though their year-to-year paths look very different. The gap between them tends to widen sharply during periods of extreme mega-cap concentration and narrow, or reverse, once market leadership broadens out again.
Is equal-weighting the same thing as investing in small-cap or value stocks?
No, though the two overlap in effect. An equal-weight fund still holds every company in its parent index, including the largest ones — it simply gives each one a similar dollar allocation rather than a size-based one. Because that structure reduces the influence of the very largest names, it ends up behaving somewhat like a mild tilt toward smaller and mid-sized companies, without actually excluding any large company from the portfolio.
Where This Fits Into a Broader Tax-Aware Portfolio
Weighting scheme is only one lever in how efficiently a portfolio behaves after taxes. Investors weighing the turnover cost of an equal-weight fund against a cap-weighted alternative are asking a version of the same question that comes up when comparing direct indexing against traditional ETFs for tax-loss harvesting: how much structural trading inside a strategy is worth tolerating for the diversification or tax benefit it delivers. The two decisions are not identical, but they rhyme — both come down to weighing a strategy’s built-in trading activity against what that activity buys you, and both are far more consequential inside a taxable brokerage account than inside a retirement account.
References
- U.S. Securities and Exchange Commission, Investor.gov: Index Funds, Investor Bulletin.
- S&P Dow Jones Indices: Official index methodology and factsheet.
- Financial Industry Regulatory Authority (FINRA): Understanding Exchange-Traded Funds.
- Internal Revenue Service: Topic No. 409, Capital Gains and Losses.
- CFA Institute Research Foundation: Research on factor investing and index construction.